Saudi Arabia’s General Authority for Competition (GAC) has made merger control a central part of its competition enforcement, and recent developments show how the regime can reach cross-border transactions. Parties planning global M&A increasingly need to understand when the Kingdom will treat an offshore deal as an economic concentration with effects in Saudi Arabia. That is why the topic of a GAC public consultation merger framework matters for deal teams: the direction of travel is toward clearer rules, but also sustained oversight. In April 2025, GAC published the fifth edition of its Economic Concentration Review Guidelines, replacing the prior guidelines and expanding transparency on what must be notified, what counts as an economic concentration, and how filings are assessed in practice.
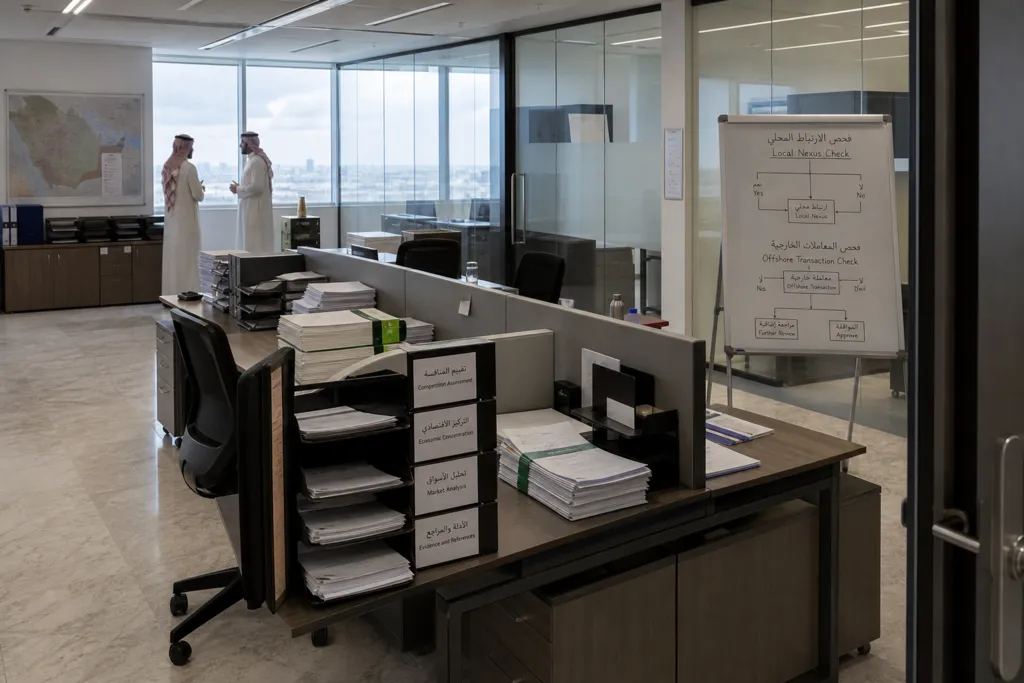
Those updates sit alongside a jurisdictional approach that explicitly captures foreign-to-foreign deals in the right circumstances. Guidance and commentary emphasize that GAC asserts jurisdiction not only over undertakings established in the Kingdom, but also over foreign-to-foreign transactions that may have a direct, substantial, and reasonably foreseeable effect on competition in Saudi Arabia. At the same time, the updated approach is framed as a move from a broader filing theory toward a more precise local nexus test. A practical example is the repeated clarification that, for acquisitions, the Saudi component must include the target’s local sales; otherwise, the transaction may fall outside GAC’s jurisdiction. In parallel, the guidelines and related commentary expanded and clarified when a joint venture constitutes a notifiable economic concentration, including more detail on full-function joint ventures.
What the Numbers Say: Record Filings and Foreign-Party Cases
GAC’s published statistics show why cross-border teams are paying close attention. In 2025, GAC reviewed 406 economic concentration applications and issued 271 No Objection Certificates following full filings, plus 135 No Notification Required Certificates for transactions not meeting notification thresholds. The total value of reviewed transactions reached about SAR 1.97 trillion, and of the 271 approvals, 269 were unconditional while two required remedies. Separately reported figures describe an average review period of 5.4 days after a filing is accepted as complete. These 2025 outcomes also included GAC’s first structural remedy in the Schlumberger–ChampionX transaction, requiring divestiture of a US subsidiary, illustrating how Saudi merger scrutiny can shape offshore deal implementation.
The mix of filings highlights the offshore angle. In the first quarter of 2025, 108 new economic concentration notifications were submitted, resulting in 64 clearances, 32 no-notification-required decisions, and two conditional clearances, with ten still under review. Those quarterly figures also showed that 80% of notifications involved foreign parties, compared with 78.20% in 2024, including foreign-to-foreign cases. Another account of 2025 filings states that foreign acquirers with a presence or impact in Saudi Arabia represented 75% of filings, with 25% involving local acquiring or merging entities. For deal planning, that split reinforces a simple point: even when the transaction is signed offshore, Saudi turnover and competitive effects can pull it into scope.
Threshold design is part of why offshore transactions can be caught, and recent reforms also aim to make the analysis more predictable. A key change described in commentary is the replacement of a former single turnover threshold with a cumulative three-part test introduced in November 2023: combined worldwide sales of at least SAR 200 million, target worldwide sales of at least SAR 40 million, and party sales in Saudi Arabia of at least SAR 40 million. April 2025 guidance further clarified that the target must contribute to the local sales threshold for acquisitions, while noting that even minimal target revenues may be sufficient. Deal teams assessing foreign-to-foreign combinations therefore need to map Saudi sales at the target level early, and also consider that GAC imposed remedies in two cases in 2025, while only four cases had remedies as of the time of writing in one contribution (two in 2023 and two in 2025).
Why does Saudi Arabia’s GAC review offshore or foreign-to-foreign transactions?
What were GAC’s headline merger control figures in 2025?
How common are foreign-party cases in recent Saudi merger filings?
What changed in the threshold framework that affects offshore deal analysis?
What is the focus of a GAC public consultation merger discussion for global deals?
Talk to us for your needs in:
-
Due Diligence and Valuation Services
-
M&A Strategy and Advisory
-
Post-Merger Integration Management
-
Regulatory and Compliance Advisory
-
Market Entry and Expansion Consulting
-
Investment and Financial Analysis
-
In-Depth Market Survey for M&A
-
Market Intelligence and Insights in M&A
-
Feasibility Study and Assessment in M&A
-
Saudi M&A Benchmarking