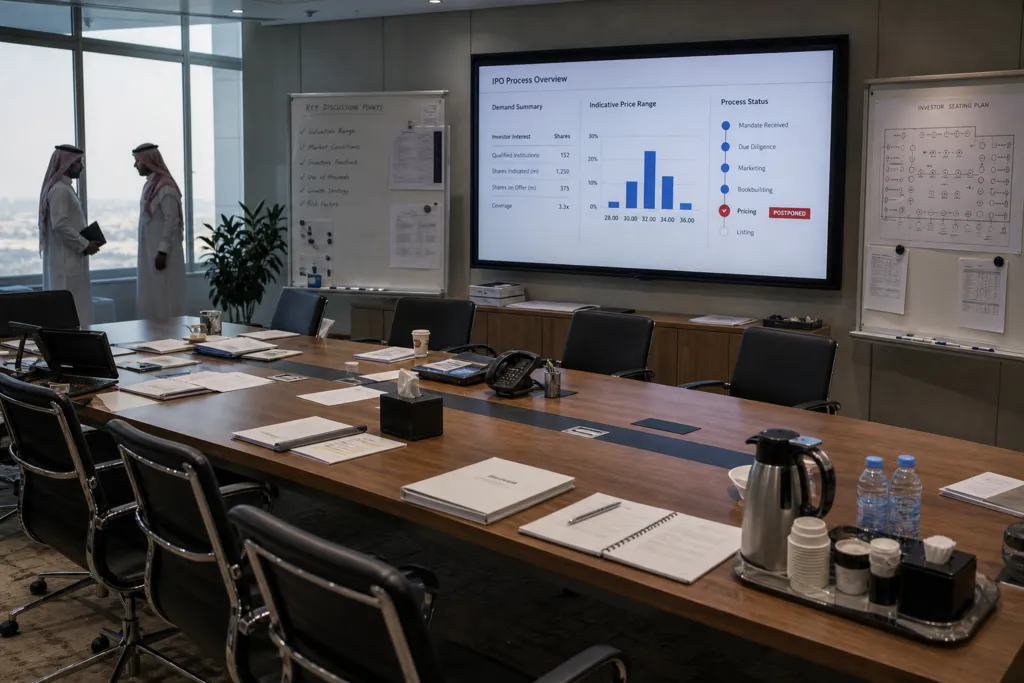
Mutlaq Al Ghowairi Contracting Company (MGC) withdrew its planned listing on the Saudi Exchange (Tadawul), shelving a deal that was aiming to raise up to SAR 3 bn through the sale of a 30% stake. The pause means the company’s CMA approval will expire without listing. The retreat has been framed by market participants as a reaction to volatility and geopolitical tensions, with a Riyadh-based investment banker saying the agreement was pulled due to market conditions and that launching when institutional investors were still “finding their footing” would have been difficult. For Saudi Arabia’s IPO pipeline, the move reinforced concerns around underwhelming subscriptions and marked-down pricing in a jittery market backdrop.
Before it was parked, the Mutlaq Al Ghowairi IPO plan was structured as a secondary sale, meaning the company itself would not receive proceeds. Instead, net proceeds would go to selling shareholders after IPO expenses of SAR 150 mn. The proposed offering size was 240 mn shares, representing 30% of the firm’s share capital, split into institutional and retail tranches. Institutional investors would initially be allocated all shares, but advisors could scale that back to 168 mn shares (70% of the offering) if retail demand was sufficient, with retail potentially receiving up to 72 mn shares (30%). The sell-down was driven by the two largest shareholders, with Mutlaq Al Otaibi set to trim his stake to 32% from 52.5% and Terad Al Ghowairi to reduce his to 15.7% from 22.5%, both subject to a six-month lock-up.
Weak Sentiment Meets Post-Listing Performance Anxiety
Reporting around the withdrawal pointed to a gap between book-building optics and secondary-market confidence. Unnamed sources cited by Bloomberg said shareholders grew concerned that ongoing instability could weigh on post-listing performance, despite institutional orders exceeding the shares on offer. Those worries reportedly intensified after some investors scaled back orders following strikes in Kuwait and Bahrain. IndexBox described the pullback as unusual because it came after finishing the institutional order-collection phase and achieving complete coverage at the top end of the indicated price range, underscoring that full coverage does not guarantee a listing if issuers doubt the market will sustain the targeted valuation once trading begins. The same period also saw Arabian Dyar reportedly pull its planned IPO amid weak sentiment, after being pitched near an SAR 16 bn valuation.
Fundamentals were part of the story, too, because contractor valuations can be sensitive to margins and backlog quality. MGC reported SAR 202 mn net income on SAR 967 mn in revenues in 1Q 2026, a net margin of 21%. Annual revenues rose from SAR 3.2 bn in 2024 to SAR 3.6 bn in 2025, but net income declined from SAR 1.2 bn in 2024 to SAR 819 mn in 2025 after dropping from SAR 1.5 bn in 2023. The company also disclosed a SAR 10.6 bn backlog at end-March, equal to a 2.7x backlog-to-revenue ratio. Water infrastructure contributed 84.2% of 2024 revenue, and around 68% of the backlog was linked to the water transmission segment, which investors may scrutinize closely when risk appetite tightens.
The broader message is that deal flow can slow even when some new listings hold up. One banker described MGC’s delay as creating a “wait-and-see dynamic,” noting that when an agreement of this size pulls back, other issuers and advisors take note as valuations are “stress-tested” and there is reluctance to proceed without clear secondary-market signals. Still, EnterpriseAM noted examples of steady post-IPO performance elsewhere on Tadawul: IT services firm Dar Albalad for Business Solutions climbed 28.21% on debut and was trading around 41% above that debut price, while mining firm Saleh Abdulaziz Al Rashed & Sons was trading roughly flat at its IPO price of SAR 45 per share. Against that mixed tape, MGC’s withdrawal became a high-profile illustration that demand concerns and valuation discipline can outweigh the momentum of a completed book-build.
Why did MGC pull the planned Tadawul listing?
How large was the planned share sale and what portion of the company was it?
How was the offering supposed to be allocated between institutional and retail investors?
What did MGC report for recent revenue, profit, and backlog figures?
What is the key takeaway from the planned Mutlaq Al Ghowairi IPO being parked after book-building?
Talk to us for your needs in:
-
Due Diligence and Valuation Services
-
M&A Strategy and Advisory
-
Post-Merger Integration Management
-
Regulatory and Compliance Advisory
-
Market Entry and Expansion Consulting
-
Investment and Financial Analysis
-
In-Depth Market Survey for M&A
-
Market Intelligence and Insights in M&A
-
Feasibility Study and Assessment in M&A
-
Saudi M&A Benchmarking